


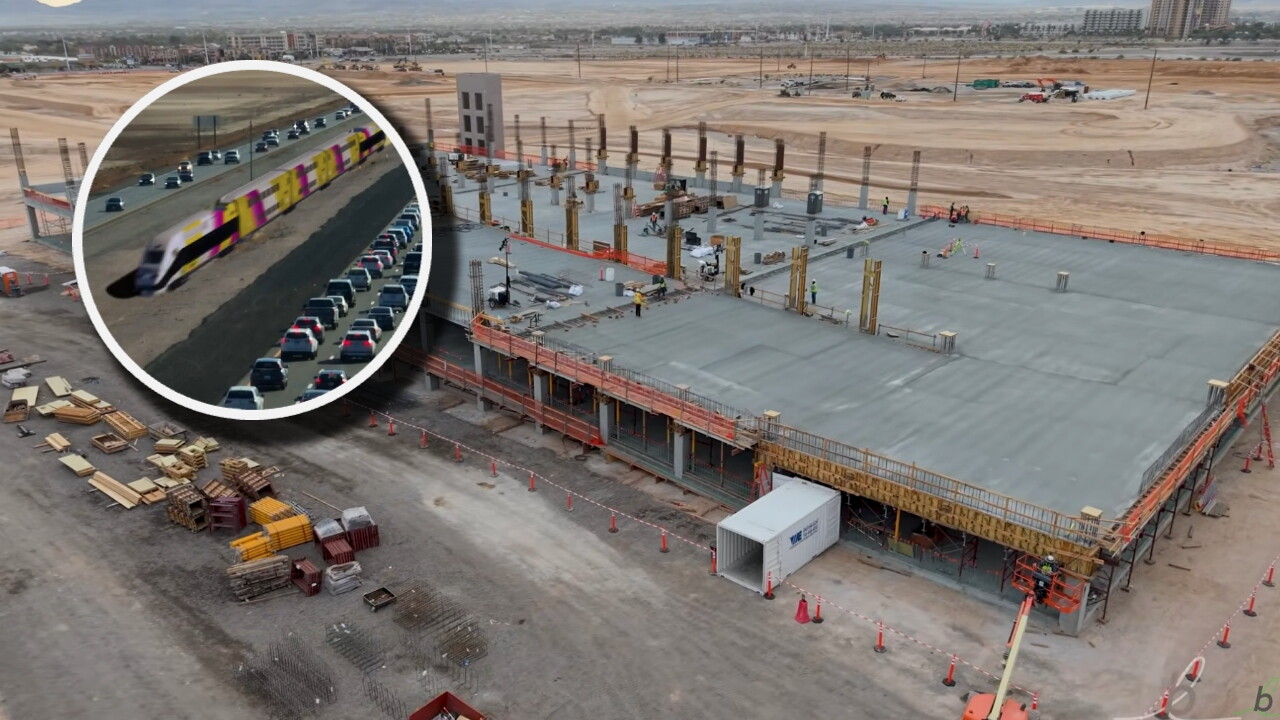

LAS VEGAS (KTNV) — Brightline Florida has filed for Chapter 11 bankruptcy protection. That's due to heavy debt because of lower ridership that what the company initially projected. This is creating more questions about what's going to happen with the Brightline West project.
While the projects are completely different businesses with separate funding, they are both owned by the same parent company, Fortress Investment Group.
Back in May, I told you that Brightline Florida currently has $5.5 billion in debt and $131 million in cash and an audit revealed "management is working to consummate one or more additional capital raises."
On Thursday, the company announced certain entities associated with the company have entered into a Restructuring Support Agreement, which will "significantly deleverage Brightline's balance sheet and greatly improve liquidity."
You can see the exact financial breakdown below.
"As part of the RSA, supporting stakeholders have committed to provide $490 million of new long term capital to Brightline Trains Florida LLC, consisting of $140 million of additional senior debt and $350 million of new junior debt. The $2.2 billion Brightline Trains Florida LLC Issue, Series 2024 (Tax-Exempt) Bonds and the existing bond insurance policy issued by Assured Guaranty will remain in place through the restructuring.
In addition, the $985 million Brightline Florida Passenger Rail Expansion Project, Series 2025B Bonds, the $925 million AAF Operations Holdings LLC Issue, Series 2024 (Tax-Exempt) Bonds and the $285.7 million AAF Operations Holdings LLC Issue, Series 2024A (Tax-Exempt) Bonds will remain outstanding, with no reduction in aggregate principal amounts, through the restructuring."
In order for all of that to happen, "certain Brightline parent entities will commence prearranged Chapter 11 processes in the United States Bankruptcy Court for the District of New Jersey," a press release reads in part.
You can see those filings by clicking here.
That being said, the company said Brightline Trains Florida LLC, which directly operates train service, will not file for Chapter 11 and will continue normal operations.
According to the company, Brightline Florida has had a 17% year-over-year increase in total revenues through the first eight months of 2026.
“Brightline is a critical part of Florida’s transportation network that has changed the way people move around the state. Today’s agreement brings $490 million in new long-term capital to Brightline from the stakeholders who know this business, and it comes at a time of real momentum,” said Patrick Goddard, Chief Executive Officer of Brightline Florida. “This transaction will be a catalyst for further growth in ridership and revenue. We are grateful to our creditors, advisors, vendors, teammates, and guests for their confidence throughout this process, and we look forward to the bright future ahead.”
When looking at the actual ridership numbers, Tim Hynes, the head of Global Credit Research at Debtwire, said Brightline's current ridership of about 3.5 million people a year that generates about $240 million of revenue is less than half the number of riders and one-third of the revenue the railroad predicted in 2024.
“The broader lesson is that intercity rail financed mainly with private high-yield debt is very hard to make work, so expect future projects to lean more on public money,” Hynes told ABC News.
What does that mean for Brightline West and the Las Vegas-Southern California train?
I reached out to Brightline West to check on the project in light of the bankruptcy news.
A spokesperson told me "whatever may be happening with Brightline in Florida would not have an impact on Brightline West or our plans for the project."
Right now, Brightline West is still working through finding financing to fully fund that project and is "remain focused on moving the Brightline West project forward."
When looking at a securities filing from earlier this month, Brightline West officials said they have "locked in the major components of the project's budget and schedule."
That document also states the remaining budget to complete the project is $20.9 billion.
"Regarding financing, the Build America Bureau remains actively engaged in its review of the project and has conducted diligence across every major aspect of the development," the filing reads in part. "The Company expects to receive an invitation to apply upon completion of the Bureau's diligence review, which the Company expects to complete no later than October of this year. The invitation to apply will begin the formal 90-day review period for the RRIF application."
Last September, Brightline West officials applied for a $6 billion loan from the federal government through the Railroad Rehabilitation and Improvement Financing program.
A source close to the matter told me the bureau is continuing to work with Brightline West to obtain information required for the creditworthiness review.
You can read the securities filing below.
As of May, Brightline West had already secured $3 billion in federal funding from the Bipartisan Infrastructure Law and $2.5 billion in private activity bonds.
Last month, Brightline West President Sarah Watterson stepped down and moved into a special advisor role as the company struggled to raise enough money to complete the project.
While the goal was for the Las Vegas to Southern California line to open in time for the 2028 Olympics, the project has been pushed back to late 2029.